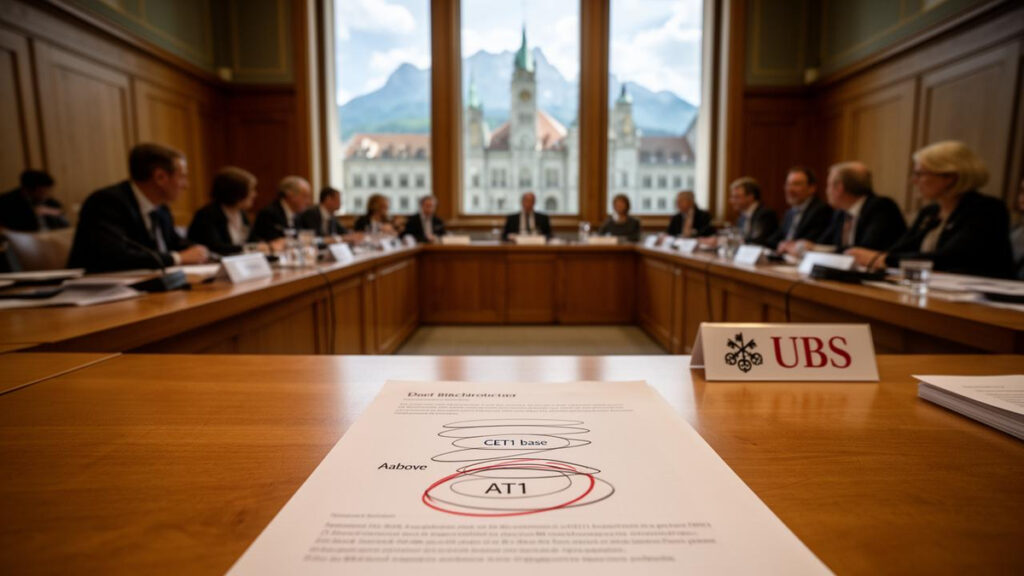
Switzerland’s parliamentary Committee for Economic Affairs and Taxation failed to reach an agreement on August 11 during deliberations on proposed new capital requirements for financial giant UBS. Following the 2023 collapse of Credit Suisse, the Swiss government presented strict regulatory proposals aimed at preventing future banking crises and protecting taxpayers. However, some lawmakers sought to ease the requirements, arguing they represent an “excessive burden.” The committee will reconvene on August 31, with plans unchanged to target a vote in the upper house of parliament in September.
The bill at the center of discussions would require UBS to hold approximately $20 billion (roughly CHF 17.3 billion) in additional Common Equity Tier 1 (CET1) capital. The measure would mandate that UBS fully meet capital allocation requirements for its foreign subsidiaries—currently set at 60%—using only CET1, whereas existing rules permit partial fulfillment using lower-cost forms of capital.
UBS has pushed back strongly against the requirement, calling it “excessive, detrimental to its competitiveness, and harmful to the Swiss banking sector.” The bank was compelled to undertake an emergency acquisition of Credit Suisse through government mediation following the latter’s collapse, and the additional capital burden weighs heavily on the post-merger integration process.
Within the committee, several amendments aimed at easing UBS’s burden were discussed. Specifically, proposals included allowing a portion of the additional capital to be met with Additional Tier 1 (AT1) capital, which is cheaper to issue than CET1, as well as introducing new regulatory triggers to enhance the loss-absorption capacity of AT1 bonds. This mechanism would halt dividend payments to investors if UBS’s capital adequacy ratio falls below a certain threshold, aiming to strengthen the safety profile of AT1 bonds.
However, while AT1 bonds are designed to absorb losses during periods of stress, regulators view them as less secure than CET1, leaving many detailed design issues unresolved. Committee member Fabio Regazzi, who belongs to a centrist party, stated, “We did not reach an agreement. We will resume discussions on the 31st,” indicating the intention to maintain the target schedule of a September vote in the upper house.
The collapse of Credit Suisse cast serious doubt on Switzerland’s financial regulatory framework. During the bank’s crisis, the Swiss government and the Swiss National Bank strongly pushed for a rescue acquisition by UBS. The massive liquidity support and loss guarantees backed by taxpayer funds exposed a de facto “too big to fail” situation, fueling public demand for tighter regulation.
The current bill, reflecting lessons learned from that episode, aims to strengthen both the quality and quantity of capital held by giant banks with overseas operations, building a system capable of withstanding future crises without relying on public funds. However, with UBS’s total assets reaching roughly twice Switzerland’s gross domestic product, concerns that excessive regulation could undermine international competitiveness persist not only within financial circles but also in parliament.
Market participants are closely watching how the final regulatory outcome will affect UBS’s capital strategy and shareholder return policies. If the full additional capital amount must be met with CET1, UBS may be forced to accumulate retained earnings or conduct capital increases, potentially leading to restrained share buybacks and dividends. Conversely, if the use of AT1 is permitted, financial flexibility would increase, though it would also depend on AT1 market trends and investor risk appetite.
The Swiss parliament’s direction could also have ripple effects on the broader European banking regulatory landscape. As the European Union advances the finalization of Basel III, discussions continue regarding capital charges for large, internationally active banks, and Switzerland’s regulatory model is likely to be referenced as a precedent.
A UBS spokesperson declined to comment on the matter. The Swiss Federal Department of Finance has also not disclosed specific views on the bill currently under parliamentary deliberation.