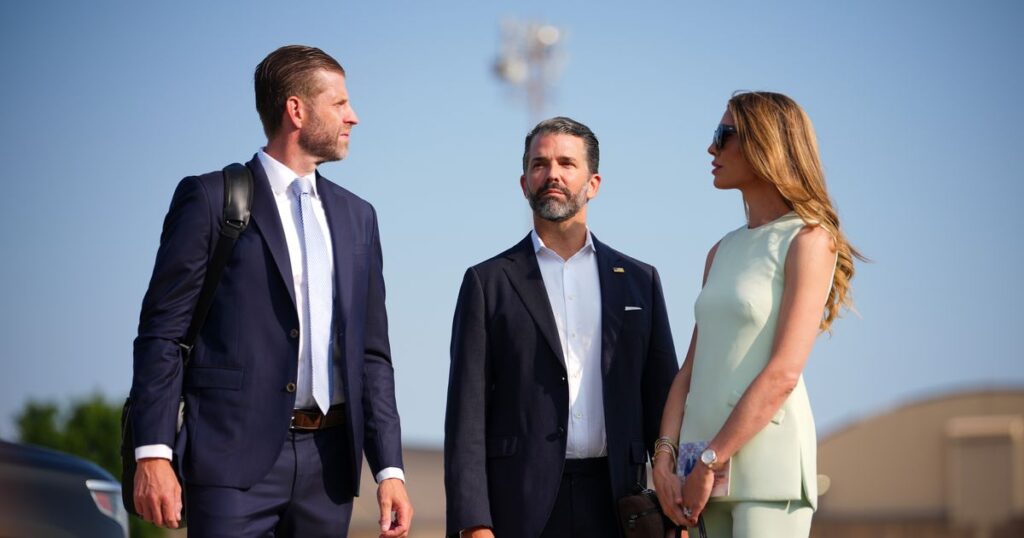
Photo: Andrew Harnik/Getty Images
Donald Trump’s second term in office has been markedly different from his first in a number of ways. In the first term, for example, the president didn’t start any new wars, while at present we’re at war with Iran. He also didn’t demolish an entire wing of the White House, nor did he use the press corps as a decoy to escape a potential assassination attempt via catering truck. A couple other differences between term one and term two? The first time around, Trump used the presidency to enrich himself to the tune of a mere $1.6 billion versus making $2.2 billion last year alone, and whereas the first time he was merely unbothered about the conflicts of interest, now he’s basically one bored weekend away from announcing a plan to subdivide the West Wing into Trump-branded condos and charge taxpayers for the work.
The most recent act of self-dealing came on Friday, when a Trump appointee at the Office of the Comptroller of the Currency — a bureau of the Treasury Department that the president has authority over — gave preliminary approval for Trump’s World Liberty Financial to operate a federally chartered trust bank, a move, per ABC News, that opens “the door for larger clients and potentially heightened profits.” The approval was specifically granted to World Liberty Trust Company, which was established in January 2026 by World Liberty Financial, a crypto venture started in 2024 by, among others, Donald Trump and his adult sons, who together own 38 percent of the business. As a reminder, it was through World Liberty Financial, and the crypto coin $WLFI, that the president made $636 million last year, while investors lost $3.81 billion through the end of June.
Anyway, here’s how the leader of the free world, Don Jr., and Eric Trump may benefit from the move, per Politico:
The decision stands to give new powers and federal credibility to a venture in which Trump and his family retain a substantial financial interest. It’s also among the most direct official actions that the administration has taken involving the president’s private finances…The approval doesn’t allow World Liberty to open a traditional bank, but rather a national trust bank — a limited-purpose institution that would not make loans or accept federally insured deposits. It’s the latest in a string of such approvals for crypto firms under Trump’s OCC. Others who have received similar green lights include Circle, Ripple and Coinbase.
The charter still provides significant legal and financial advantages. It’ll allow World Liberty to issue and redeem its USD1 stablecoin directly, manage the reserves backing it and offer digital asset custody services without relying on an intermediary. The company could also operate across state lines more easily without having to answer to individual state regulators.
Democratic lawmakers are unsurprisingly not thrilled about the decision. “This is the most brazen act of self-dealing our financial system has ever seen — and Congress cannot allow it to stand,” Senator Elizabeth Warren, the ranking member on the Senate Banking Committee, declared on Friday. Warren, along with a group of colleagues including Bernie Sanders, Andy Kim, Chris Murphy, and Richard Blumenthal, has said she will introduce a bill that states “no President, Vice President, their immediate families, or other senior government officials can exploit their positions to own or control a bank, which could serve as a major vehicle for corrupt dealings.” An aide told Politico the committee would “likely probe the OCC’s approval of the World Liberty bank charter next year if Democrats regain control of Congress.” In a statement, Donald Sherman, the CEO of watchdog Citizens for Responsibility and Ethics in Washington, called the approval “the most egregious example to date of the President’s businesses profiting from his government job.”
World Liberty and the White House, of course, insist there is absolutely nothing to see here except a president who loves his country and would never take advantage of his position to make money. Before the approval was granted, the crypto venture declared that there are no conflicts of interest because Trump is not involved in the company’s management, and none of its employees work for the federal government. (That the Trumps own 38 percent of the thing is apparently neither here nor there.) A spokeswoman for the White House previously told ABC News the president “only acts in the best interests of the American public” and that “there are no conflicts of interest” because “President Trump’s assets are in a trust managed by his children.” Which one could argue doesn’t make it very blind, but who’s to say.
Daily news about the politics, business, and technology shaping our world.
Vox Media, LLC Terms and Privacy Notice