
Fresh interest in PBF Energy (PBF) follows BlackRock’s recent Schedule 13G filing tied to the refiner’s stock. This development surfaced just after an earnings report that sharply exceeded consensus expectations and a strong recent share price move.
That earnings surprise has arrived after a powerful run in the shares, with the stock posting a 90 day share price return of 58.46% and a year to date share price gain of 195.37%. The 1 year total shareholder return of 212.14% highlights how strongly momentum has built around PBF Energy despite a 1 day pullback of 5.67%.
Capture this refiner momentum by lining up PBF Energy beside other hand picked plays in the sector with 28 high quality undervalued stocks.
PBF Energy looks like a strong refiner on recent results and sector momentum, yet the share price has raced far ahead in a short window. How much of that strength is already baked into today’s valuation?
Most Popular Narrative: 11% Overvalued
On the most followed narrative, PBF Energy screens as overvalued, with a fair value of $75.69 against a last close of $84.27, which puts the rapid share price move and the analyst target gap into sharper focus.
Net global demand for refined products is expected to exceed net refining capacity additions in the coming years, driven by ongoing population growth and underinvestment in new refining capacity outside North America. This tightening supply backdrop should support strong utilization, pricing power, and higher revenues for efficient U.S. refiners like PBF.
See why 16 investors see PBF Energy as 11% overvalued.
Result: Fair Value of $75.69 (OVERVALUED)
Still, persistent refinery reliability issues and pressure from decarbonization policies could chip away at the PBF Energy investment case faster than bullish narratives assume.
Find out about the key risks to this PBF Energy narrative.
Another View: PBF Energy On Earnings Multiples
The narrative flags PBF Energy as 11% overvalued against a $75.69 fair value, yet the current P/E of 7.4x tells a different story. The stock trades below both the US Oil and Gas industry at 12.1x and peers at 33.1x, and even under its own 9x fair ratio. This points to valuation risk being tilted toward pessimistic expectations rather than stretched optimism. That raises a simple question for investors: is the crowd too cautious about what this refiner can sustainably earn?
See what the numbers say about this price — find out in our valuation breakdown.
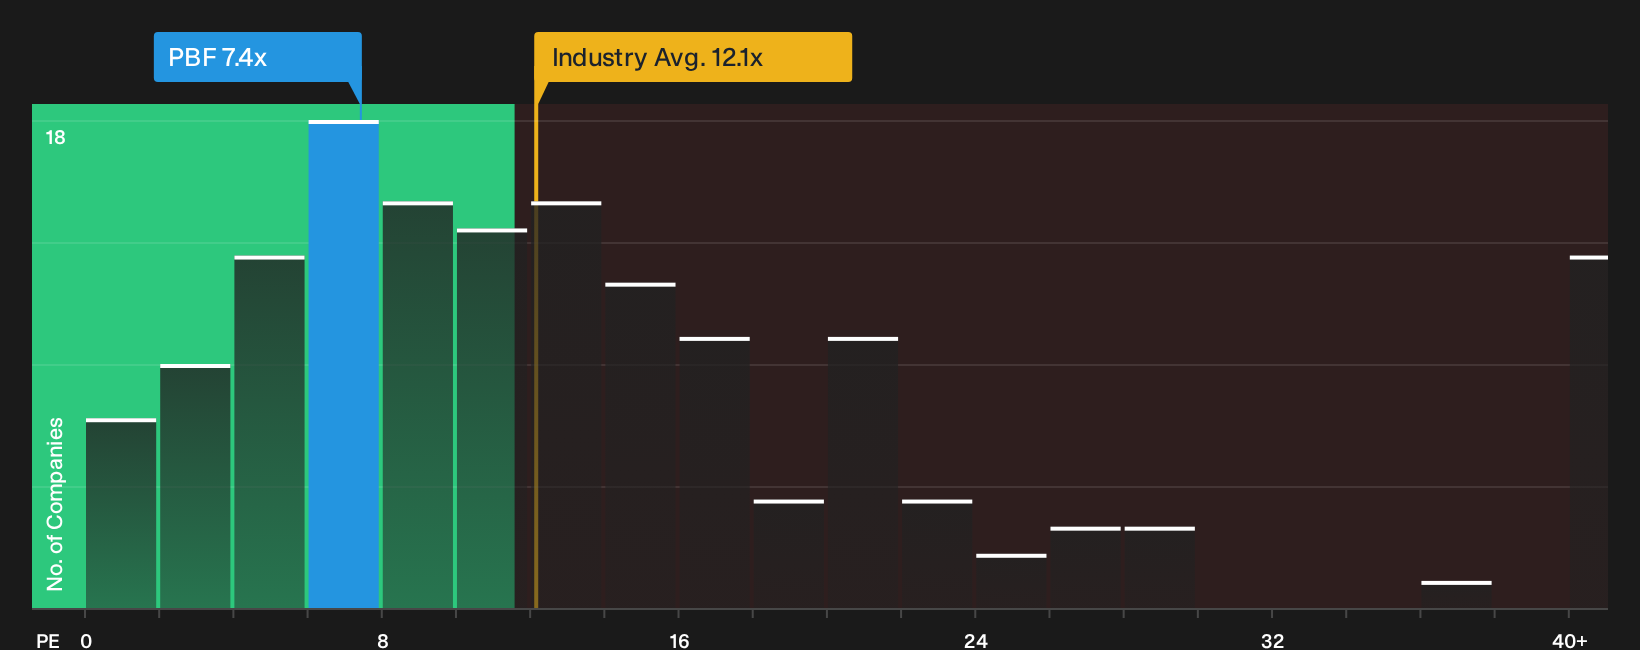 NYSE:PBF P/E Ratio as at Oct 2026Next Steps
Sentiment on PBF Energy is mixed, with strong recent returns on one side and valuation questions on the other. Consider both perspectives using the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond PBF Energy?
If PBF Energy has your attention, do not stop there. Broaden your watchlist with other opportunities that line up with your goals and risk comfort.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com