
Romania’s mergers and acquisitions (M&A) market recorded 212 transactions in the first nine months of 2026, down slightly from 215 deals in the same period last year, according to an analysis by EY. Despite the 1% decline in transaction volume, the estimated value of the market increased by 33% to USD 7.1 billion, from USD 5.4 billion in the first nine months of 2025. The value of disclosed transactions rose by 39% to USD 4.1 billion, driven largely by three major acquisitions announced in the first half of the year.
The three largest transactions were Paval Holding’s USD 977 million acquisition of Carrefour Romania, Premier Energy’s USD 824 million acquisition of Evryo Group, and Raiffeisen Bank International’s USD 681 million acquisition of Garanti BBVA Romania. Together, they accounted for approximately 60% of the total disclosed deal value during the period.
M&A activity slows in the third quarter
Romania’s performance followed a broader international trend of higher transaction values despite declining deal volumes. Across Europe, M&A value increased by 54% in the first nine months of 2026, while global deal value rose by 28%. Meanwhile, transaction volumes fell by 11% in Europe and 8% globally.
Following a particularly strong first half, global M&A activity slowed in the third quarter, with total deal value falling below USD 1 trillion for the first time since Q2 2025, according to LSEG. Only ten transactions exceeding USD 10 billion were announced worldwide, the lowest quarterly number of mega-deals since Q4 2024. The slowdown came amid rising energy costs, renewed inflationary pressures, and higher expectations for long-term interest rates.
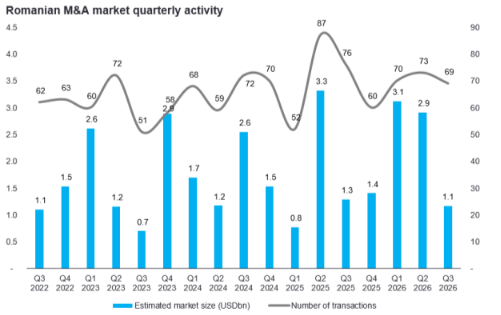
Romania also recorded weaker M&A activity in Q3 2026, with transaction volume down 9% and disclosed deal value falling 15% compared with the same quarter in 2025. No transactions exceeding USD 100 million were announced during the quarter.

One notable deal was the acquisition of Pall-Ex Romania by BoldMind Capital Partners and the company’s executive management team through a leveraged buyout valued at approximately USD 29 million. Pall-Ex Romania provides domestic and international palletised freight distribution services as part of a wider European network.
Another significant regional development, although outside the scope of EY’s Romanian M&A database, was Canadian group Alimentation Couche-Tard’s announced voluntary tender offer for Żabka Group, Poland’s largest convenience retailer. Żabka operates more than 13,000 stores across Poland and Romania, including the Froo convenience store chain on the Romanian market. The offer implied an equity valuation of approximately USD 8.6 billion.
Foreign investors drive deal activity
Strategic investors remained the dominant buyers in Romania’s M&A market, accounting for 83% of transaction volume during the first nine months of 2026.
Direct acquisitions by financial sponsors declined by 17% year-on-year, with more than one-third involving transactions across multiple countries. However, when acquisitions by private equity-backed companies are also considered, financial sponsor-backed buyers accounted for approximately 28% of total deal volume.
Cross-border investment continued to play a significant role. Inbound acquisitions increased by 13% year-on-year to 124 transactions, while domestic deals declined by 10% to 78.
Inbound acquisitions also exceeded the 70 transactions involving disposals by foreign-owned businesses, indicating that foreign investors continued to expand their presence in the Romanian market.
The United States remained the leading source of foreign investors, with 16 transactions, followed by France and Austria with 11 each. The United Kingdom ranked fourth with seven deals, while Poland followed with six.
Real estate and technology lead by deal volume, while energy storage attracts investment
Real Estate, Hospitality & Construction remained the most active sector, with 46 transactions during the first nine months of 2026.
Technology, Media & Telecommunications (TMT) ranked second with 40 deals, maintaining its position from the corresponding period of 2025. Nearly a quarter of TMT transactions involved technology acquisitions spanning multiple countries, while the telecommunications segment accounted for just one deal.
Advanced Manufacturing & Mobility followed with 37 transactions, up 37% year-on-year. The increase was driven entirely by stronger activity in advanced manufacturing, as mobility deal volumes remained unchanged. Foreign buyers accounted for approximately two-thirds of the sector’s transactions.
Energy & Utilities ranked fourth with 30 deals, approximately half of which involved foreign acquisitions of battery energy storage system (BESS) projects, reflecting investor interest in Romania’s developing energy storage market.
Consumer Products & Retail and Health & Life Sciences each recorded 19 transactions, representing annual declines of 32% and 41%, respectively. The decrease in healthcare-related M&A followed an active period in 2025, when the market recorded a high number of veterinary clinic acquisitions.